On this page
Every year, Nigerians living in London, Houston, Toronto, Dubai and other parts of the world send substantial sums home. For many, property is the most tangible way to invest in Nigeria, whether the objective is a future home, rental income, capital preservation, family use or long-term wealth.
But buying property from thousands of kilometres away is fundamentally different from buying something you can visit every weekend. You cannot simply drive to the site. You may be relying on video calls, photographs, relatives, agents and documents sent electronically.
And when something goes wrong, you may discover the problem months or years after the money has changed hands.
The biggest mistake is therefore not buying property from abroad. It is buying property from abroad using a process built on trust rather than verification.
“The biggest mistake is not buying property from abroad. It is buying property from abroad without independent verification.”
Featured residences
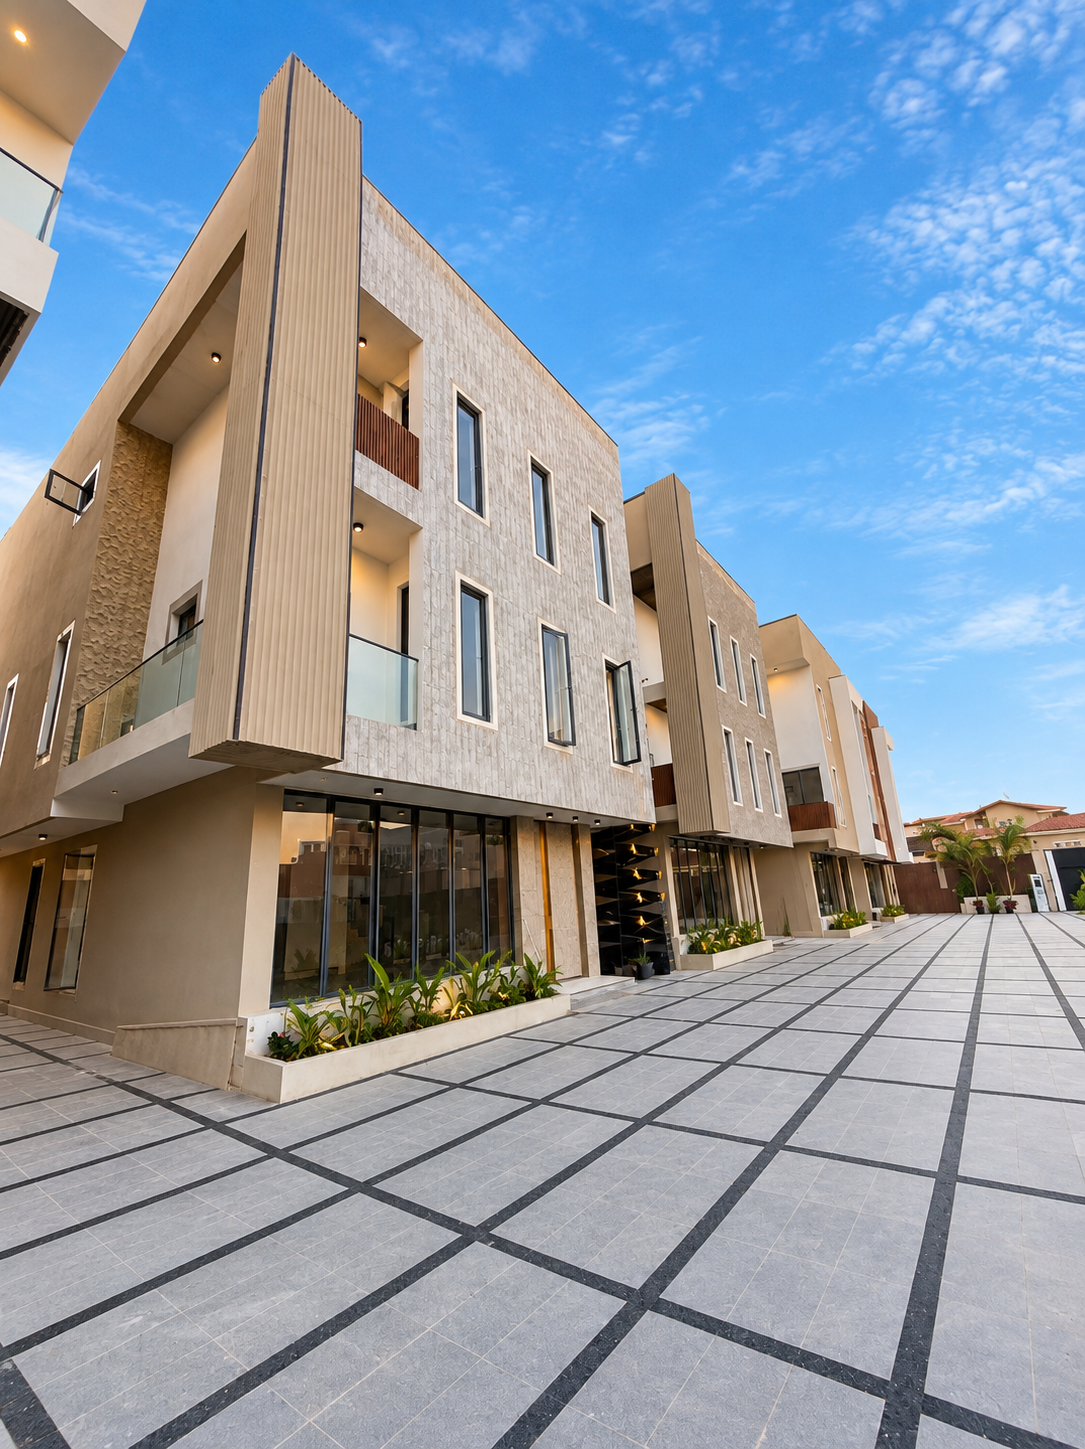
Ikoyi
4 & 5 Bedroom Duplex in Parkview Estate, Ikoyi
From ≈ US$1.24M (indicative)
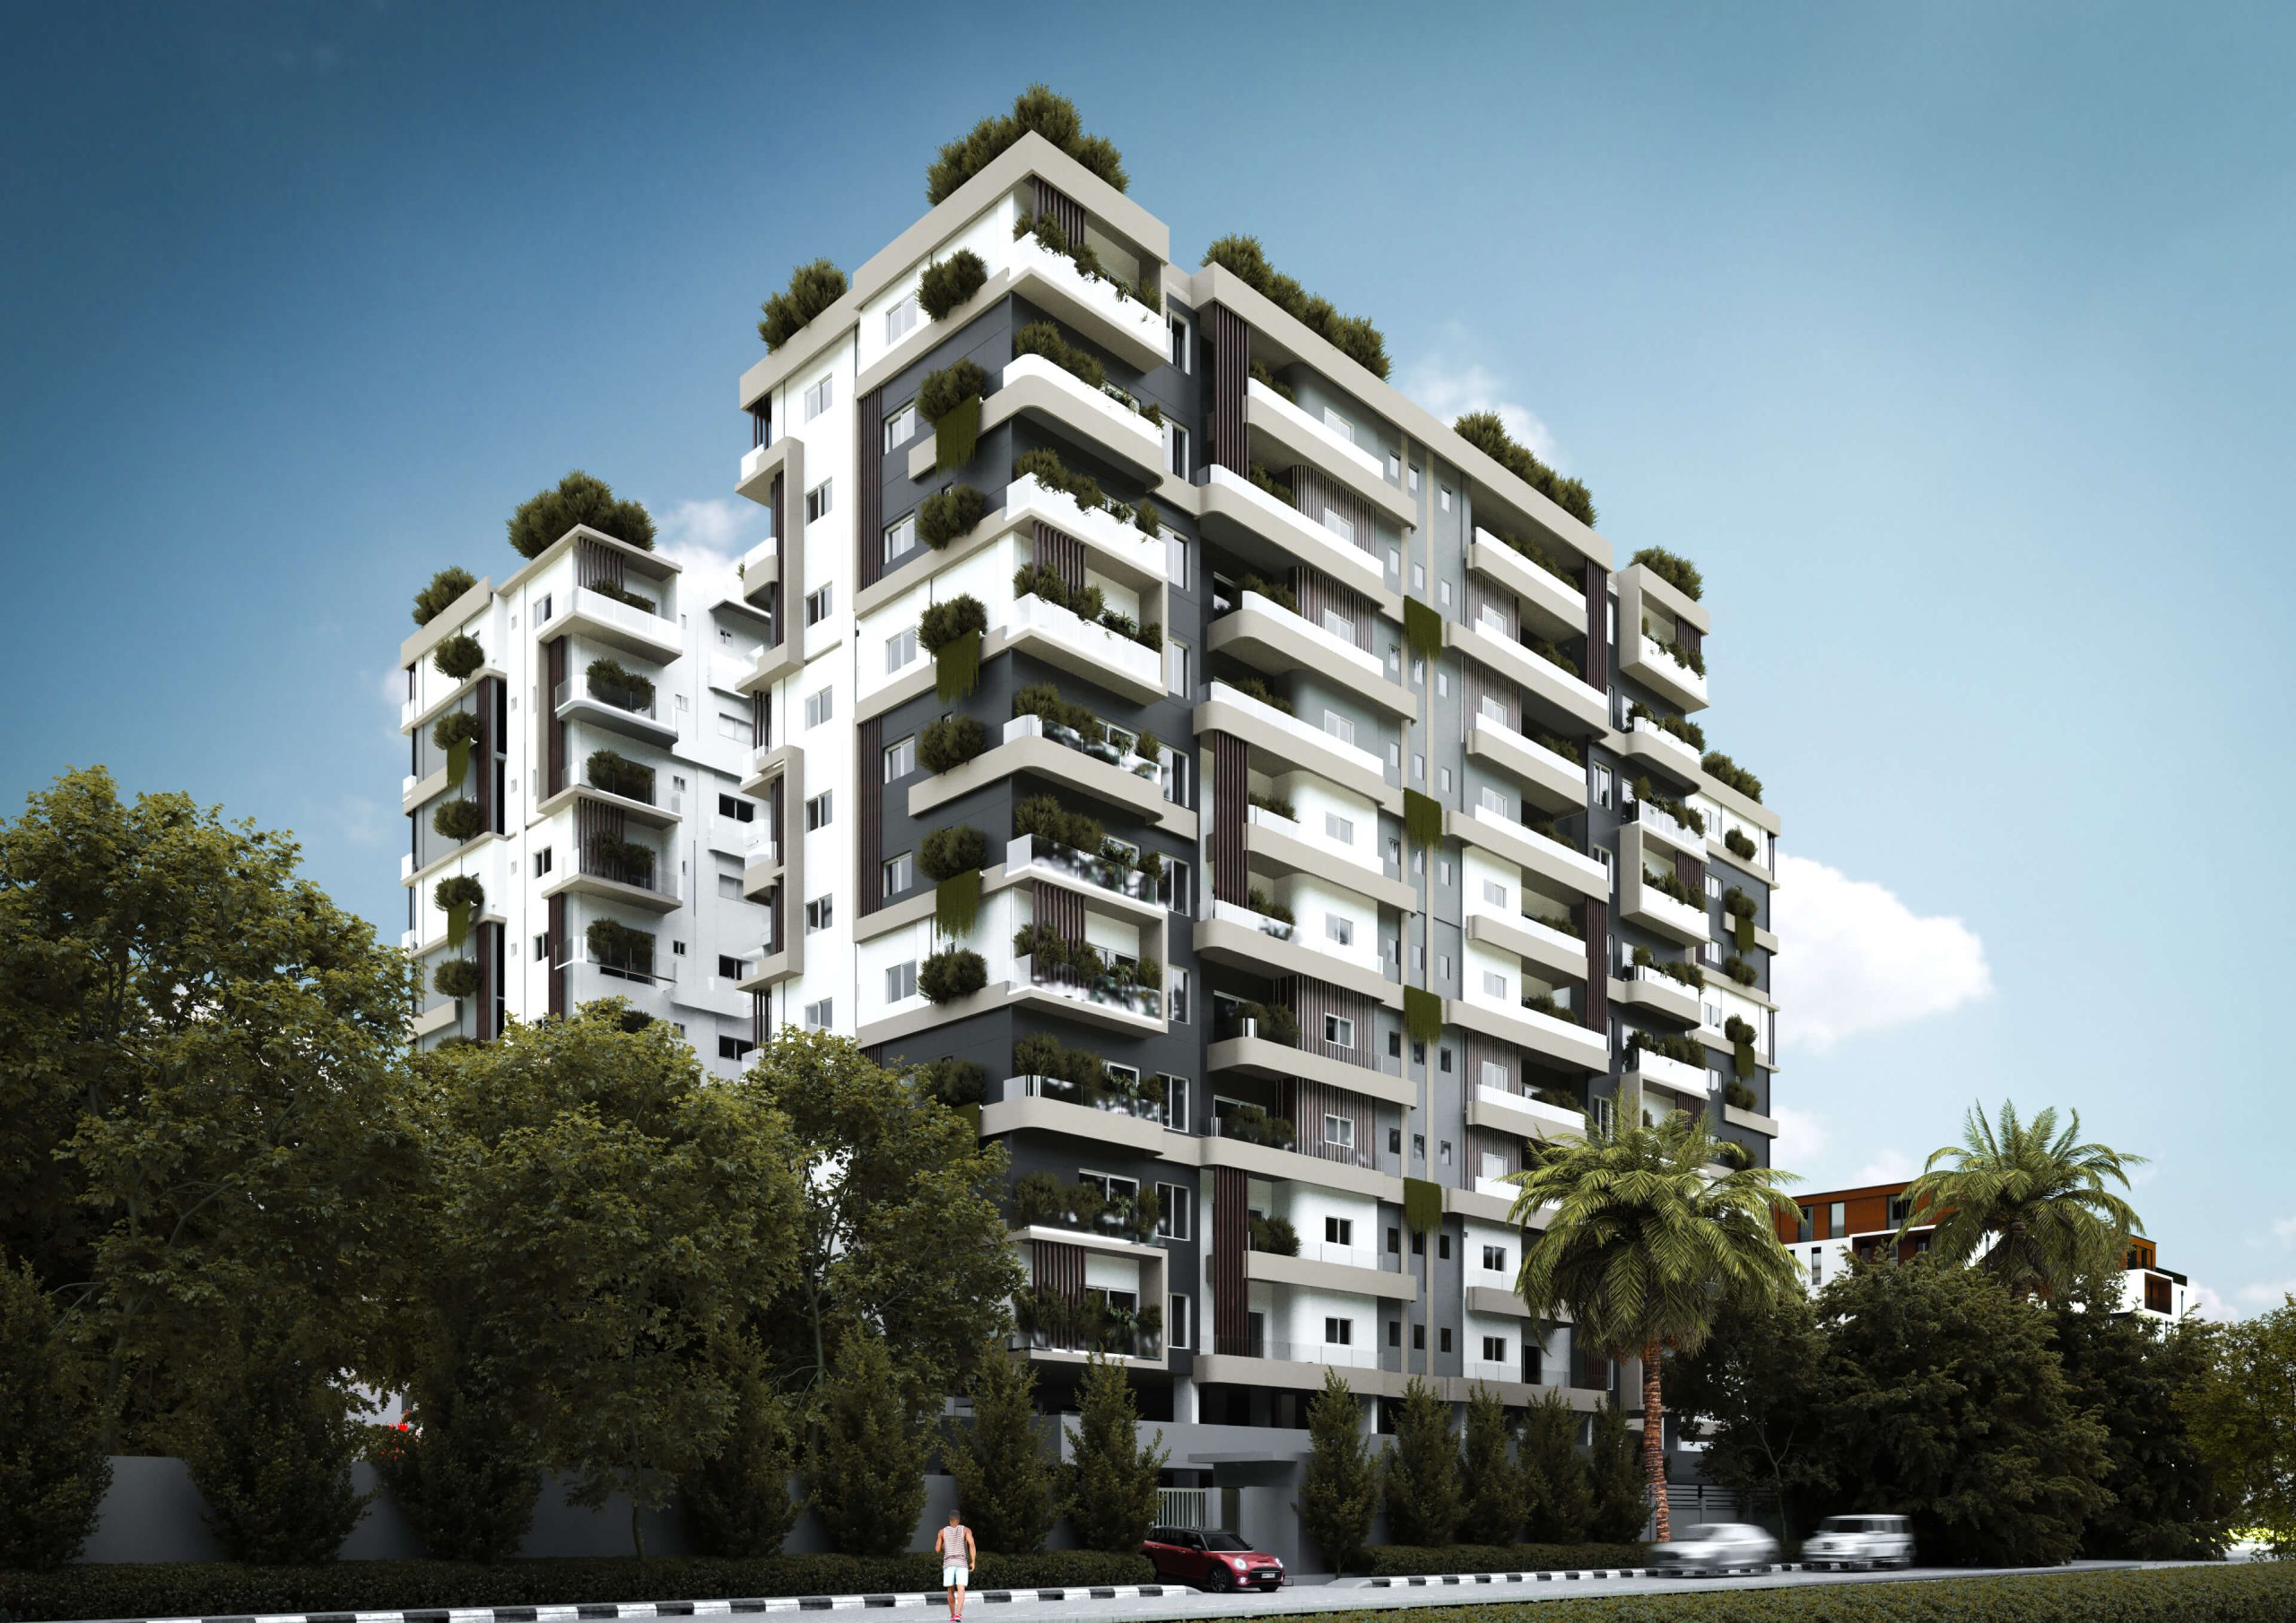
Ikoyi
Luxury 3 Bedroom Apartments in Ikoyi
From US$534,902
Banana Island
Luxury 5 Bedroom Waterfront Villas in Banana Island
From US$2,500,000
The Parkview residences is priced in Naira; USD shown at ₦1,375/$1 for guidance only.
Context
The diaspora property opportunity
Nigerians abroad are a significant part of the country’s financial ecosystem. The figures below are published by official institutions and are provided for context rather than as a projection of property performance.
NRNOA + NRNIA
Non-resident Nigerian ordinary and investment account structures introduced by the Central Bank of Nigeria.
Source: Central Bank of NigeriaSources and methodology
Remittance figures are as published by the Central Bank of Nigeria, and the share of GDP is as reported in World Bank data. Reporting periods, revisions and measurement methods differ between institutions, so the figures should be read as published context rather than a single continuous series. They describe financial flows into Nigeria and do not measure property returns.
Mistake 01
1. Trusting a relative instead of conducting independent due diligence
“My brother is in Lagos.” “My uncle has inspected it.” “My cousin knows the developer.” “The agent was introduced by someone I trust.” These are the most common sentences in remote property purchases, and they are all describing familiarity rather than verification.
A relative may confirm that a building physically exists. That does not establish:
- who owns the land
- whether the seller has authority to sell
- whether the title is genuine
- whether the property falls within the titled land
- whether the development is approved
- whether there are encumbrances
- whether the developer has complied with planning requirements
“Someone you trust can inspect a property. They should not replace independent due diligence.”
Looking for verified Lagos property? Explore the developments currently offered through AOP Homes.
Explore propertiesMistake 02
2. Falling in love with the property before checking the title
Beautiful photography, sea views, rooftop lounges, swimming pools, gyms, luxury finishes and an attractive payment plan are designed to secure a decision. Title investigation is then treated as a formality to complete afterwards.
Reverse the sequence.
The considered sequence
The costly sequence
Key takeaway
The finish level of an apartment can be assessed at any time. The legal position should be established before money is committed.
Mistake 03
3. Assuming the C of O or Governor’s Consent automatically covers the property you are buying
The distinction that matters most
A genuine title document does not automatically prove that the physical property you are buying sits entirely within the land covered by that title.
Documentary title
What the paperwork says about the land: the interest granted, the parcel described, the registered owner and any recorded restrictions.
Physical property
What actually exists on the ground: the building, its footprint, its boundaries and its position relative to the described parcel.
The two should be reconciled. Title due diligence answers legal questions about the land; survey verification answers physical questions about the property. Neither exercise substitutes for the other, and a remote buyer needs both.
Verification
The document must match the land
- 01Title document
- 02Survey plan and coordinates
- 03Registered surveyor
- 04Physical site
- 05Actual building
An appropriately registered surveyor should be instructed to verify that:
- the physical property corresponds with the relevant survey
- the boundaries match
- the coordinates correspond
- the building sits within the titled parcel
- the development has not extended beyond the land covered by the title
- the developer has not occupied neighbouring land
- the development has not encroached into road setbacks
- the development has not encroached into drainage corridors or other restricted areas
“Do not only ask whether the title is genuine. Ask whether the property is actually the property covered by the title.”
When the developer builds beyond the title
A developer may hold legitimate title to a parcel while the physical development extends beyond the relevant boundaries. Common examples include:
- building beyond the surveyed boundary
- extending into road setbacks
- occupying drainage corridors
- extending into government reservations
- constructing structures on adjoining land
- creating a building footprint larger than permitted
Title boundary
The land described by the title document and survey.
Actual development footprint
Where the built footprint extends past the boundary, the excess area is a potential encroachment and requires professional verification.
Diagram for illustration only. A discrepancy does not automatically mean demolition; it means the position should be established by qualified professionals before purchase.
A buyer should not assume that a building is compliant simply because it has been completed or occupied.
Need help assessing a property before you commit? Speak with an AOP Homes adviser.
Speak with an adviserMistake 04
4. Checking that the building you see is the building that was actually approved
The question is not simply whether the developer has building approval. The better question is whether the completed building corresponds with the approval.
Buyers should ask to see and independently review the relevant:
- development permit
- approved architectural drawings
- approved site plan
- survey plan
- structural documentation where relevant
- amendments
- completion documentation
- fitness-for-habitation documentation where applicable
- other regulatory approvals applicable to the property
A developer may have obtained approval for one development and later constructed something materially different:
- approval for fewer floors, but more floors constructed
- approval for a smaller footprint, but a larger structure constructed
- approval for one use, but another use adopted
- approved setbacks not maintained
- additional structures constructed without corresponding approval
- approved configuration changed materially during construction
Approved
- 3 floors
- 4 units
- Approved footprint
Actual
- 6 floors
- 8 units
- Larger footprint
Illustrative example of an approval mismatch, not a specific development.
Key takeaway
The existence of an approval is not the same as compliance with the approval.
Regulatory risk
Why planning non-compliance can become a future problem
Construction that does not conform to approvals may expose property owners to regulatory enforcement. Depending on circumstances, consequences can include:
- enforcement notices
- restrictions
- penalties
- inability to regularise
- difficulty selling
- financing difficulties
- partial removal
- removal or demolition in appropriate cases
Depending on the nature and circumstances of the contravention, enforcement can include partial or total removal. Not every discrepancy leads to that outcome, and the Lagos State Building Control Agency sets out the framework that applies in Lagos.
Lagos State Building Control Agency
The road and drainage problem buyers often do not see
Rapid development creates pressure to maximise the building footprint. A developer may build close to or beyond road setbacks, drainage channels, government reservations or infrastructure corridors. Lagos authorities have documented enforcement against structures on drainage paths and government setbacks.
“The extra square metres may look like added value until you discover that they were never lawfully available for development.”
Mistake 05
5. Assuming a C of O means everything is fine
A Certificate of Occupancy or Governor’s Consent is an important title document, but title due diligence should investigate the whole documentary chain and any relevant encumbrances, including:
- ownership
- authority to sell
- registered interests
- mortgages
- restrictions
- competing claims
- acquisition status
- relevant consents
- survey correspondence
Key takeaway
A C of O is not meaningless and it is not conclusive. It is an important document, but it is one part of a wider due-diligence exercise.
Mistake 06
6. Buying because property prices are rising
An asking price is what a seller hopes to achieve. It is not evidence of what comparable properties have actually transacted for. A remote buyer who relies on advertised prices alone has no measure of the market.
A more complete assessment considers:
- actual comparable transactions
- rental income
- vacancy
- service charges
- maintenance
- liquidity
- resale
- location
- infrastructure
- future supply
Consider a simple illustration. Two apartments are offered at the same price in the same neighbourhood. One is in a well-managed building with reliable power, steady tenant demand and a moderate service charge. The other has a higher service charge, longer vacancy periods and more limited resale interest. The advertised price is identical; the ownership experience and eventual exit are not.
Illustration only. It is not a forecast, a valuation or a statement about any specific property, and past appreciation does not indicate future returns.
Mistake 07
7. Ignoring the total cost of acquisition
Property price
₦250,000,000
Plus, depending on the transaction
- Legal feesTransaction-specific
- Agency feesTransaction-specific
- Registration and perfection costsTransaction-specific
- Statutory charges where applicableTransaction-specific
- FurnishingTransaction-specific
- RenovationTransaction-specific
- Service chargesTransaction-specific
- Property managementTransaction-specific
- InsuranceTransaction-specific
- FX and conversion costsTransaction-specific
Figures are not stated as fixed percentages because they vary by property, title status, professional and location. Ask for a written breakdown for your specific purchase.
“A ₦250 million property is not necessarily a ₦250 million investment.”
Mistake 08
8. Sending money before the documentation is ready
Remote purchases often invert the order of the transaction because the buyer wants to secure a unit quickly. The preferred sequence is straightforward.
Preferred
Not this
Before funds move, establish:
- payment trail
- recipient identity
- payment purpose
- contractual milestones
- refund provisions
- conditions precedent
- escrow or structured payment where appropriate
This is general due-diligence guidance, not financial, tax or legal advice.
Mistake 09
9. Buying off-plan without investigating the developer
Off-plan purchases require the buyer to assess both a future residence and the developer’s ability to deliver it. Examine:
- corporate identity
- previous projects
- delivery history
- title to the development land
- planning approvals
- project documentation
- contractual obligations
- completion obligations
- refund provisions
- service charges
- assignment restrictions
“Do not only ask whether the developer has built before. Ask what they built, where, when and under what title and approval structure.”
Our detailed framework for this is set out in the off-plan property guide.
Explore developments currently available through AOP Homes.
View propertiesMistake 10
10. Ignoring currency risk and property management
Currency
Buyers abroad typically earn in USD, GBP, CAD or EUR, while a Nigerian property may be priced and generate income in naira. Naira appreciation in property value and performance measured in a foreign currency are not necessarily the same thing, and exchange-rate movements affect both the purchase and the income.
Management
Ownership from abroad only works with a named plan for who will:
- inspect the property
- collect rent
- handle repairs
- pay service charges
- monitor tenants
- maintain documentation
- manage the property day to day
- prepare it for resale
The AOP Homes diaspora due-diligence test
Before you send the money, can you answer yes?
Interactive checklist
0 of 13 answered yes
If you cannot confidently answer these questions, you may not have completed your due diligence.
Framework
The AOP Homes property verification framework
01
Title
Who owns the land?
02
Survey
Does the physical property correspond with the titled land?
03
Planning
Was the development properly approved?
04
Compliance
Does the completed building correspond with the approval?
05
Transaction
Are the contract, payment structure and transfer documentation properly recorded?
06
Management
Who will protect and manage the asset after completion?
Conclusion
The goal is not to make property buying complicated. It is to make it verifiable.
Buying property in Nigeria from abroad does not have to mean buying blindly. The opportunity is real, and Nigerians abroad continue to play a significant role in the country’s financial and investment ecosystem.
But distance changes the way property should be bought. The more remote the buyer, the more important independent verification becomes.
Do not verify only the document. Verify the document against the land. Do not verify only that an approval exists. Verify the building against the approval.
Do not ask only whether the property exists. Establish what exactly exists, where it sits, what it is approved for and what legal interest you are actually acquiring.
That is the difference between simply buying Nigerian real estate and making an informed property decision.
How we think about property
Verification before promotion
- Verification before promotion
- Documentation before payment
- Independent professional checks
- Clear transaction information
- Long-term client relationships
AOP Homes is a property brokerage and advisory business. We do not provide legal or surveying services. Where those functions are required, buyers should engage appropriately qualified independent professionals.
FAQ
Frequently asked questions
Can Nigerians living abroad buy property in Nigeria?
Yes. Nigerians resident outside the country can generally acquire property in Nigeria, and many do so for family use, future relocation, rental income or long-term holding. The practical difference is process rather than permission: a buyer who cannot attend site, meetings and registry searches in person should rely on independent professionals and documented verification instead of informal assurances.
How can I verify a property title in Nigeria?
Title verification should be carried out by an independent lawyer instructed by you, not by the seller. It normally involves examining the documentary chain of ownership, conducting the relevant searches at the appropriate land registry, confirming the seller’s authority to sell, and checking for registered interests or restrictions. Documentary title work should be supported by physical survey verification.
Is a C of O enough when buying property in Nigeria?
A Certificate of Occupancy is an important title document, but it is one part of a wider due-diligence exercise. It does not by itself confirm the seller’s authority to sell, the absence of encumbrances, the planning status of the development, or that the building you are buying sits entirely within the land the document covers.
Should I use a surveyor when buying property in Nigeria?
Engaging an appropriately registered surveyor helps establish whether the physical property corresponds with the relevant survey and title: whether boundaries and coordinates match, whether the building sits within the titled parcel, and whether the development has extended into adjoining land, road setbacks or drainage corridors.
How do I know if a developer’s building approval covers the property?
Ask for the development permit and approved drawings, then compare them with what has actually been built: number of floors, footprint, use, setbacks and any additional structures. An approval that exists is not the same as an approval that has been complied with, and any material difference should be explained and professionally reviewed before you commit.
Can a property be demolished if it does not comply with building regulations?
Depending on the nature and circumstances of the contravention, enforcement can include partial or total removal. Not every discrepancy leads to demolition; outcomes range from enforcement notices and penalties to restrictions or removal. Lagos State Building Control Agency materials set out the enforcement framework that applies in Lagos.
What should Nigerians abroad check before buying off-plan property?
Confirm the developer’s corporate identity and delivery record, the title to the development land, the planning approvals for the specific scheme being sold, the sale agreement and specification, how payments relate to construction milestones, the refund and delay provisions, service-charge obligations, and the documents due at handover.
What are the hidden costs of buying property in Nigeria?
Beyond the purchase price, buyers should budget for legal fees, agency fees, registration and perfection costs, statutory charges where applicable, furnishing or renovation, service charges, property management, insurance and currency conversion costs. Rates vary by transaction, so ask for a written breakdown for your specific purchase rather than assuming a standard percentage.
E-E-A-T
Research and sources
- Central Bank of Nigeria — remittance data and non-resident account structures
- World Bank — personal remittances as a share of GDP
- Lagos State Building Control Agency — building control and enforcement
- Lagos State Government — physical planning, development permits and land administration
Reviewed by AOP Homes Advisory
This advisory is prepared for informational purposes and is based on publicly available regulatory, financial and real estate information. Property-specific decisions should be supported by appropriate legal, surveying, valuation and other professional due diligence.
This article is for general information and does not constitute legal, surveying, valuation, tax or investment advice. Buyers should obtain independent professional advice appropriate to their transaction.
Published September 2026 · Last reviewed September 2026 · AOP Homes Advisory